Is it optional to know what an option is? No.
This note takes someone who can do calculus, differential equations, and a stats course, and builds the Black–Scholes–Merton formula in seven stages. No finance and no stochastic calculus are assumed; both are built. We take the stages in order.
Roadmap
- What is an option? A rain check: the right to buy at a strike. Payoff at expiry is arithmetic. Today's premium is the question.
- Martingales, Wiener, stocks. A Wiener process (Brownian motion) is the noise. A martingale is a fair game. A stock is the ODE $dS=\mu S\,dt$ plus that noise, scaled by $S$ so the price stays positive.
- Lognormal properties. Multiplicative returns add in log space; the CLT makes $\ln S_T$ Gaussian. Density, Jacobian, median versus mean, $\mathbb{E}[e^{aZ}]=e^{a^2/2}$.
- A simple calculus argument. Given that lognormal, completing the square turns $\mathbb{E}[(S_T-K)^+]$ into two $\Phi$'s, in parameters $(m,s)$. Then each assumption is perturbed: what morphs the formula, and what breaks it.
- A detour to Japan. The chain rule throws $(dx)^2$ away. For Wiener that term is the same size as $dt$, so Itô keeps it. Quadratic variation, Taylor in two variables, $d(W^2)=2W\,dW+dt$.
- Derive from stochastic calculus. Itô on $\ln S$ produces the lognormal with $m=\ln S+(\mu-\tfrac12\sigma^2)\tau$. Replication (a two-leaf tree) and Girsanov replace $\mu$ by $r$. Plug in: the rain check is $10.45$. The PDE is the same Gaussian, as heat.
- Change of numeraire. $\Phi(d_2)$ is exercise probability in dollars. $\Phi(d_1)$ is exercise probability in shares. One more Girsanov, tilt $-\sigma$.
- 1. What is an option?
- 2. Martingales, Wiener, stocks
- 3. Lognormal properties
- 4. A simple calculus argument
- 5. A detour to Japan
- 6. Derive from stochastic calculus
- 7. Change of numeraire
- Limitations
- References
The change-of-numeraire calculation follows Fabrice Douglas Rouah, Four Derivations of the Black-Scholes Formula. The original host is gone. A copy is here; the Wayback capture of 19 July 2024 is the provenance.
1. What is an option?
In ordinary English, optional means you do not have to. In finance that is almost the definition.
An option is a contract that gives its owner the right, and not the obligation, to buy or sell something at a pre-agreed price. The something is the underlying — a share of stock, a bushel of wheat. The pre-agreed price is the strike, written $K$. The deadline is expiry, written $T$. For that right you pay money up front, the premium. The rest of this note is the question: what must the premium be?
You already know the everyday version. A rain check that lets you buy a TV at today’s price next month is a call option on the TV. If the store drops the price, you ignore the rain check and buy cheaper. If the store raises the price, you use the rain check. You will only exercise when it helps you. That one-sidedness is the whole point.
Calls and puts
A call is the right to buy the underlying at the strike. It pays you when the underlying finishes above $K$. A put is the right to sell the underlying at the strike. It pays you when the underlying finishes below $K$.
Every contract has two sides. The buyer (the holder, long the option) pays the premium today and owns the right. The seller (the writer, short the option) captures that premium today and takes on the matching obligation. Whatever the buyer can choose to do, the writer can be forced to do. The buyer’s profit is the writer’s loss, dollar for dollar.
To see the cash move, fix a working premium of $10$. We do not yet know whether $10$ is the right price — that is the rest of the note — but we need a number to subtract. A stock trades at $100$ today. Strike $K=100$, expiry in one year.
The call buyer
You pay $10$ today. One year later the stock is at $S_T$.
- If $S_T=130$, you exercise. The writer must sell you the share at $100$. You now hold something worth $130$ that you paid $100$ for, so the contract paid $30$. Subtract the $10$ you already spent: net $+20$. Or: buy at $100$ via the call, immediately sell in the open market at $130$.
- If $S_T=80$, exercising would mean paying $100$ for a share worth $80$. You are not required to be that foolish. You let the ticket expire. The $10$ is gone. Net $-10$.
- If $S_T=100$, exercising gains you nothing. You walk away. Net $-10$.
Unlimited upside (the stock can in principle go to the moon). Limited downside (the worst case is losing the premium). That is why people buy calls.
The call writer
Someone took the other side. They received your $10$ today and promised: if you choose to buy at $100$, I must sell at $100$.
- If $S_T=80$ or $S_T=100$, the buyer walks away. You keep the $10$. Net $+10$. Collect premium, option expires worthless: the writer’s dream.
- If $S_T=130$, the buyer knocks. You must sell a $130$ share for $100$.
- If you already owned the share (covered call): you hand it over at $100$ instead of selling it in the market at $130$. You missed $30$ of upside, but you had pocketed $10$, so net $-20$.
- If you did not own it (naked call): you buy at $130$, sell to the buyer at $100$, lose $30$, offset by the $10$. Net $-20$.
Limited upside (the premium is the most you can make). Unlimited downside (the stock can go to the moon, and you still have to sell at $100$). Writing naked calls is a dangerous way to “collect premium.” A covered call is the version to picture first: you already own the stock, you are willing to let it get called away, and the premium is extra income if it does not.
Break-even for both sides is $S_T=110$: the stock has to rally $10$ just to recoup the $10$ you paid (or, for the writer, that is where the obligation starts to eat the premium).
| \(S_T\) | Call buyer (paid 10) | Call writer (captured 10) |
|---|---|---|
| 70 | expires, −10 | keeps premium, +10 |
| 100 | expires, −10 | keeps premium, +10 |
| 110 | exercise, 10 − 10 = 0 | obligation, 10 − 10 = 0 |
| 130 | buy at 100, sell at 130: +20 | must sell at 100 a share worth 130: −20 |
| 150 | +40 | −40 |
Each row sums to zero. That is the bet.
The put, briefly
A put is the other flavor. You have paid a premium (call it $8$ for this paragraph) for the right to sell the share at $100$. The clean cash picture: buy the stock low in the open market, then sell it high to the put writer at the strike.
- If $S_T=70$, you buy in the market for $70$, exercise the put, the writer is forced to buy at $100$. Pocket $30$, minus the $8$. Net $+22$.
- If $S_T=130$, nobody will let you sell a $130$ share to them at $100$. You throw the put away. Net $-8$.
A put is not a mystical “bet against.” It is a coupon that says: if this thing gets cheap, I may purchase it cheaply in the market and put it to you at the old high price.
| \(S_T\) | Put buyer (paid 8) | Put writer (captured 8) |
|---|---|---|
| 70 | buy at 70, put at 100: +22 | must buy at 100 a share worth 70: −22 |
| 100 | expires, −8 | keeps premium, +8 |
| 130 | expires, −8 | keeps premium, +8 |
The rest of this note prices the call. The put will fall out later from an accounting identity, not a second integral.
Payoff versus profit
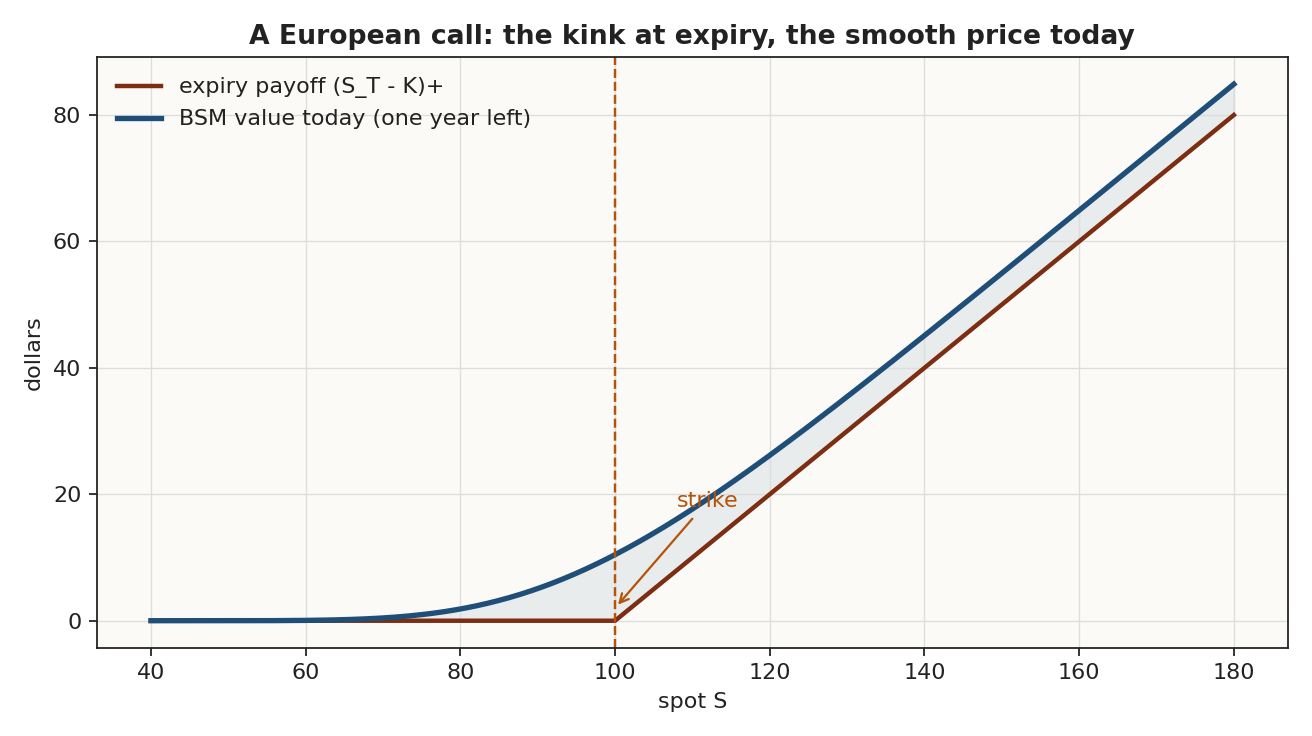
The payoff is what the contract hands you at expiry, before subtracting the premium. For the call buyer that is $\max(S_T-K,\,0)$; for the put buyer, $\max(K-S_T,\,0)$:
\[(S_T - K)^+ \;=\; \max(S_T - K,\, 0).\]The profit is payoff minus premium for the buyer, and premium minus payoff for the writer.
| Stock at expiry \(S_T\) | Call payoff \(\max(S_T-100,\,0)\) | Put payoff \(\max(100-S_T,\,0)\) |
|---|---|---|
| 70 | 0 | 30 |
| 100 | 0 | 0 |
| 120 | 20 | 0 |
| 150 | 50 | 0 |
When $S_T>K$ the call is in the money (the put is out). When $S_T<K$ the call is out of the money (the put is in). When $S_T=K$ both are at the money. Nicknames for the rows.
A European option may be exercised only at the single instant $T$. An American option may be exercised on any day up to and including $T$. For a call on a stock that pays no dividend, Merton’s theorem says you should never exercise early, so the two prices agree. We price the European call.
At expiry the payoff is arithmetic. The hard question is today’s premium. That depends on how $S$ wanders. Stage 2 is the language of that wander.
2. Martingales, Wiener, stocks
Three objects. A source of noise, a notion of a fair game, and a model of the stock built from both.
Wiener process
A Wiener process — also called Brownian motion, written $W_t$ — is the model of pure noise used in this note. Picture a pollen grain on a water surface, or a walker who at every instant takes a tiny random step up or down. The walker’s height at time $t$ is $W_t$.
It is not a stock price. It starts at $0$, it is as likely to be negative as positive, and its typical size at time $t$ is $\sqrt{t}$, not $t$.
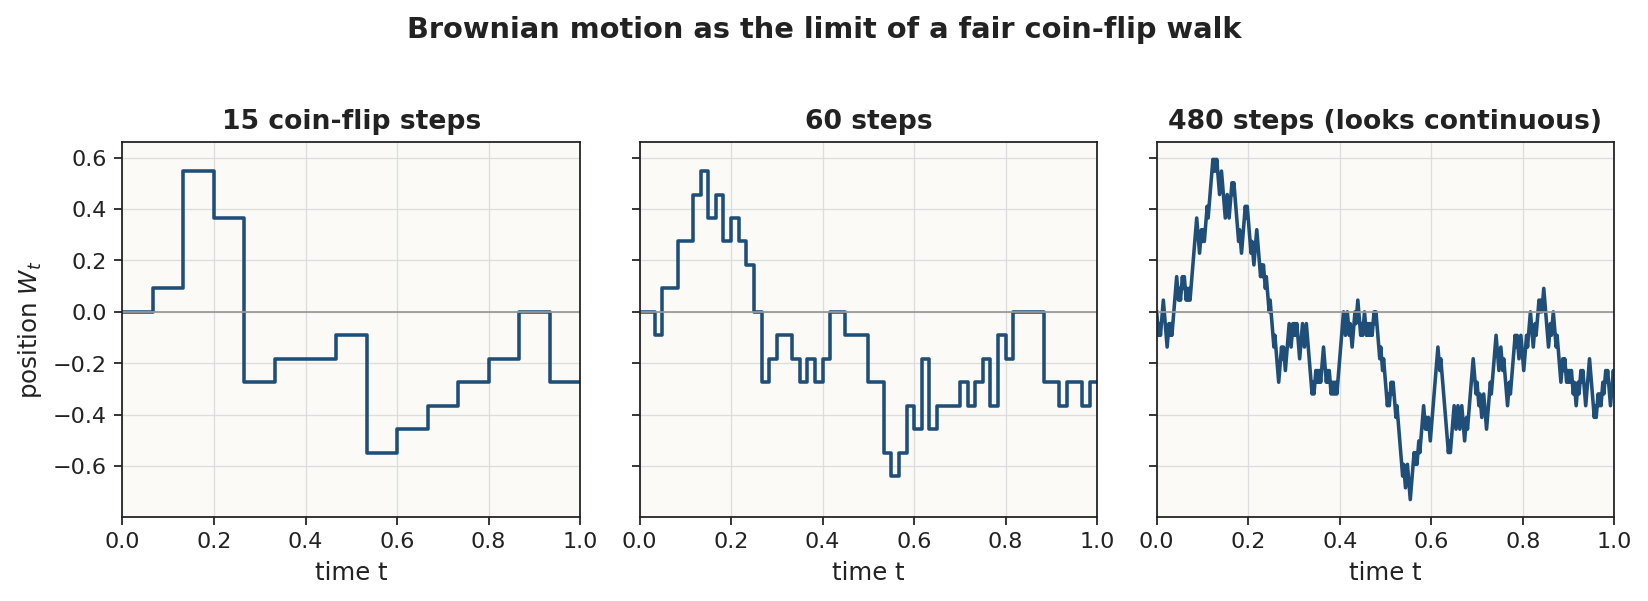
Coin-flip construction. Fix a horizon $T$ and chop it into $n$ pieces of length $\Delta t=T/n$. Flip a fair coin at each tick. On heads walk up $\sqrt{\Delta t}$; on tails walk down $\sqrt{\Delta t}$. After time $t=k\,\Delta t$,
\[W_t^{(n)} \;=\; \sqrt{\Delta t}\,(\xi_1+\cdots+\xi_k), \qquad \xi_i=\pm 1 \text{ with equal probability}.\]Each step has mean $0$ and variance $\Delta t$, so $k$ steps have mean $0$ and variance $t$. The CLT says that for large $n$ the position at a fixed $t$ is approximately $\mathcal{N}(0,t)$. Send $n\to\infty$ and the staircase becomes a continuous scribble. That scribble is $W_t$.
Four properties. A standard Wiener process satisfies:
- $W_0=0$.
- Independent increments. For $t>s$, $W_t-W_s$ does not depend on the path before time $s$.
- Gaussian increments. $W_t-W_s\sim\mathcal{N}(0,\,t-s)$. In particular $W_t\sim\mathcal{N}(0,t)$, so $\mathbb{E}[W_t]=0$ and $\mathrm{Var}(W_t)=t$. The typical size is $\sqrt{t}$. Over a short interval the typical move is $\sqrt{\Delta t}$, much larger than $\Delta t$ when $\Delta t$ is small.
- Continuous paths. No jumps. A jagged scribble with no breaks.
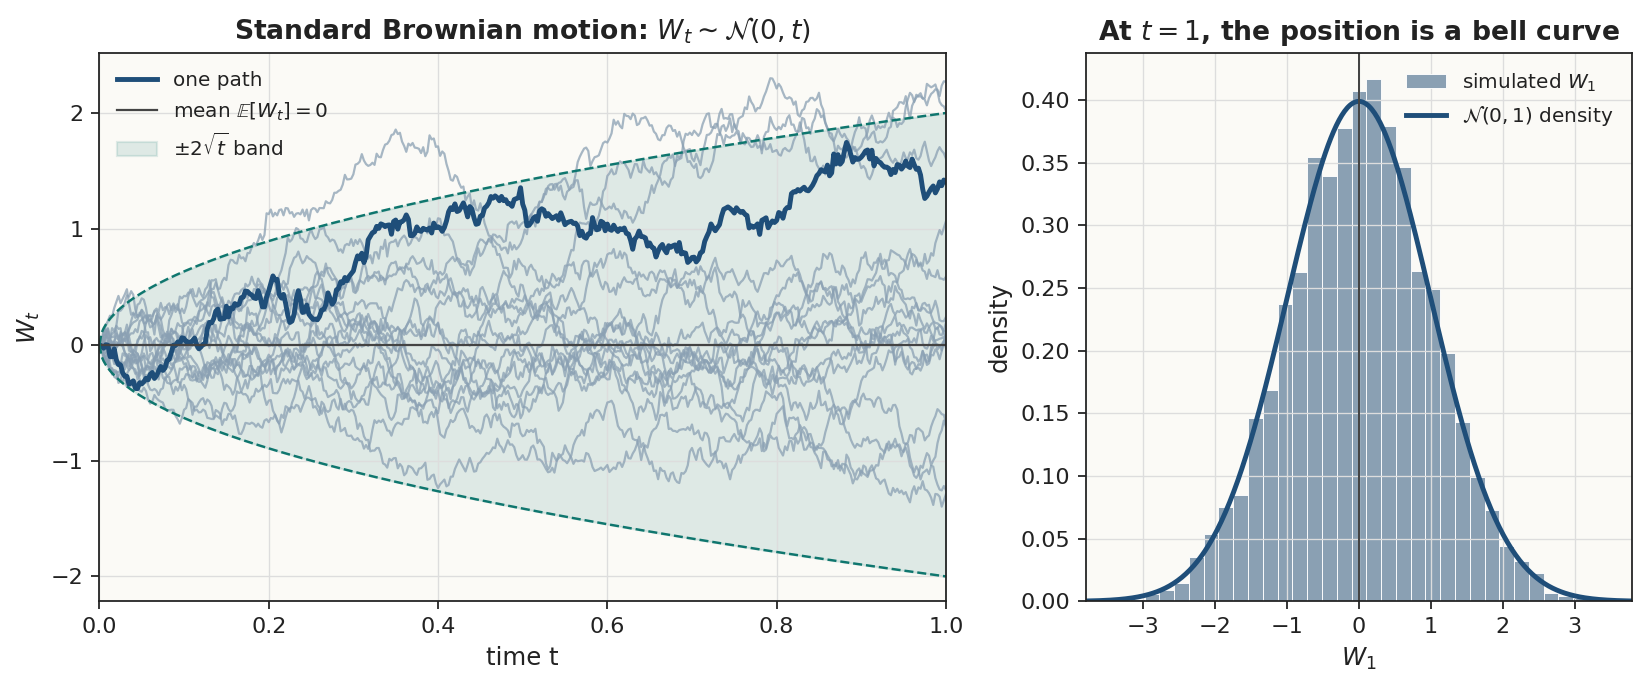
On the left, paths start at $0$ and wander equally above and below — several are negative, which a stock cannot be. The shaded trumpet is $\pm 2\sqrt{t}$. On the right, many runs stopped at $t=1$: the $\mathcal{N}(0,1)$ density.
Write $dW_t$ for an increment over an instant $dt$. Property 3 says $dW_t$ is about $\mathcal{N}(0,dt)$, so $(dW_t)^2$ is typically of size $dt$, not $(dt)^2$. Stage 5 is why that leftover must be kept. For now, the multiplication table, as a fact about this process:
\[dt\cdot dt \to 0, \qquad dt\cdot dW_t \to 0, \qquad dW_t\cdot dW_t \to dt.\]Martingales
A stochastic process is a family of random variables indexed by time — a random path. A process $M_t$ is a martingale if
\[\mathbb{E}[M_T\mid \text{information up to time }t] \;=\; M_t.\]A martingale is a fair game. Given what you know now, you should not expect to win or to lose.
Wiener itself is a martingale: $\mathbb{E}[W_T\mid W_t]=W_t$, because the remaining increment has mean $0$ and is independent of the past. The physical stock will not be a martingale — it has a drift, which is why anyone bothers to own it. Pricing will live on a different assignment of probabilities, under which the discounted stock is a martingale. That assignment is stage 6. The definition is here so the word is not magic later.
Stocks
$W_t$ is a bad model for a stock. It can be negative, and a $$100$ stock and a $$10$ stock should not make dollar moves of the same typical size.
You already know the ODE $dS=\mu S\,dt$, whose solution is $S_t=S_0 e^{\mu t}$. The model used here is that ODE plus noise, scaled by the current price so the percentage move is Wiener. That is geometric Brownian motion:
\[dS_t \;=\; \mu S_t\,dt + \sigma S_t\,dW_t. \tag{2}\]Read it as a recipe for a short interval $dt$:
- a deterministic fraction $\mu\,dt$ (the drift $\mu$ is the expected rate of return);
- plus a random fraction $\sigma\,dW_t$ (the volatility $\sigma$ scales the Wiener increment).
Because the noise is multiplied by $S_t$, a $$200$ stock has twice the dollar volatility of a $$100$ stock, and $S_t$ stays positive. The $d$ on the left is an increment, not a derivative.
The solution of $(2)$ is not $S_0 e^{\mu t}$ times a noise factor. Stage 5 will correct the exponent. Stage 3 is the distribution of $S_T$ that that solution will have: lognormal.
A dollar in the money-market account (riskless savings at a constant rate $r$) grows as $B_t=e^{rt}$. Continuous compounding: $e^{0.05}\approx 1.0513$ over a year.
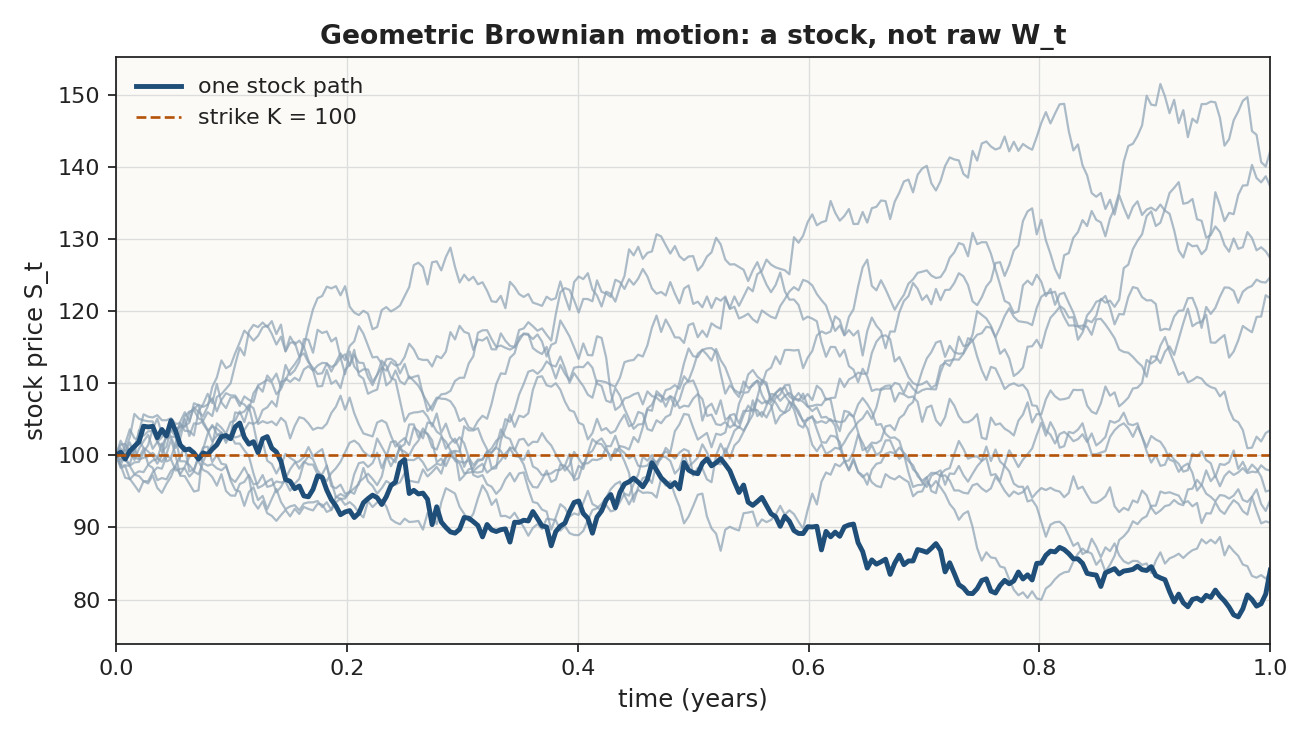
Each path is one draw of $W$, turned into a price by $(2)$. A European call with the dashed strike pays the excess over $100$ if the path ends above the line, and zero otherwise.
3. Lognormal properties
A stock is a product of returns, not a sum of dollars. Over a day the price multiplies by a gross return $1+R_i>0$. Over $N$ days
\[S_T \;=\; S \prod_{i=1}^{N}(1+R_i), \qquad \ln S_T \;=\; \ln S + \sum_{i=1}^{N}\ln(1+R_i).\]The logs add. If the daily log-returns are independent with finite mean and variance, the CLT says their sum is approximately Gaussian. Therefore $\ln S_T\sim\mathcal{N}(m,s^2)$ for some $m,s$, and
\[S_T \;=\; e^{Y}, \qquad Y\sim\mathcal{N}(m,s^2).\]A positive random variable whose logarithm is Gaussian is lognormal. Two objections to an additive Gaussian for the price are gone: $S_T>0$ always, and doubling $S$ doubles $S_T$.
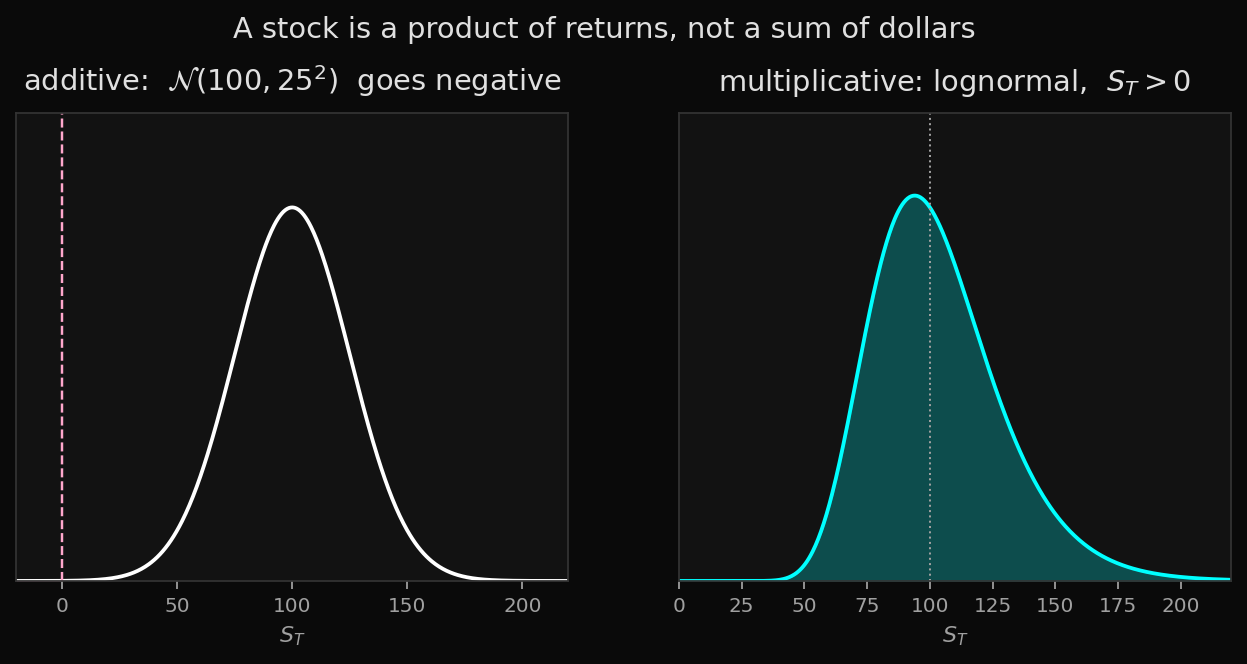
Write $Y=m+sZ$ with $Z\sim\mathcal{N}(0,1)$. The median of $S_T$ is $e^{m}$. The mean is not $e^{m}$: $x\mapsto e^{x}$ is convex, so Jensen gives $\mathbb{E}[e^Y]>e^{\mathbb{E}[Y]}$. The exact gap is the moment-generating function of a standard normal. Completing the square:
\[\mathbb{E}[e^{aZ}] \;=\; \int_{-\infty}^{\infty}\frac{1}{\sqrt{2\pi}}\exp\Bigl(az-\frac{z^2}{2}\Bigr)\,dz \;=\; e^{a^2/2},\]because $az-z^2/2=-\tfrac12(z-a)^2+a^2/2$, and what remains is a normal density with mean $a$. Hence
\[\mathbb{E}[S_T] \;=\; e^{m+s^2/2}.\]For $s=0.20$, $e^{0.02}\approx 1.0202$: a twenty-percent log-vol inflates the mean by about two percent relative to the median. Picture: $S=100$, $s=0.20$, $m=\ln 100+0.03$. Median $\approx 103.0$, mean $\approx 105.1$. The typical path ends near $103$; the average is pulled up by the right tail. That $e^{s^2/2}$ is Itô’s correction, first as an MGF. Stage 5 recovers it from Taylor.
The density of $S_T$ follows from $y=\ln x$, $dy=dx/x$:
\[f_{S_T}(x) \;=\; \frac{1}{s\, x\sqrt{2\pi}}\exp\Bigl(-\frac12\Bigl(\frac{\ln x-m}{s}\Bigr)^2\Bigr), \qquad x>0.\]The extra $1/x$ is the Jacobian. The cdf is Gaussian in log-coordinates: $P(S_T\le K)=\Phi\bigl((\ln K-m)/s\bigr)$, where $\Phi(x)=P(Z\le x)$ for $Z\sim\mathcal{N}(0,1)$, and $\Phi(-x)=1-\Phi(x)$.
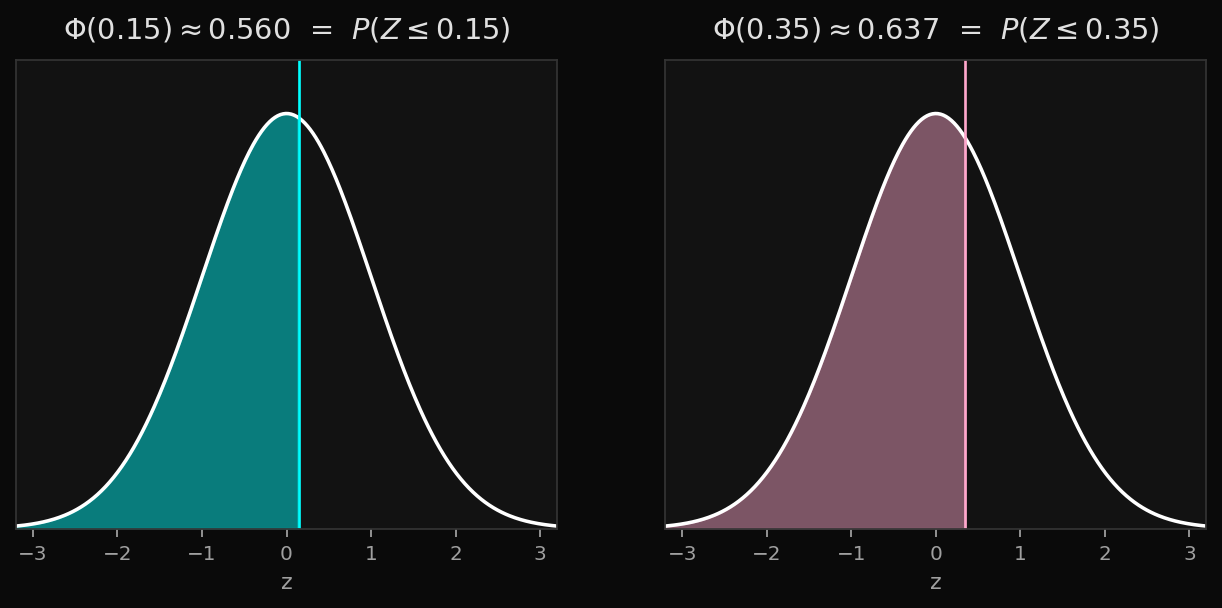
Stage 6 will identify $m=\ln S+(\mu-\tfrac12\sigma^2)\tau$ and $s=\sigma\sqrt{\tau}$ from the SDE $(2)$. For stage 4 we treat $(m,s)$ as given and compute the call by calculus.
4. A simple calculus argument
Assume $S_T$ is lognormal, $Y=\ln S_T\sim\mathcal{N}(m,s^2)$. Split the payoff on ${S_T>K}$:
\[\mathbb{E}[(S_T-K)^+] \;=\; \mathbb{E}\bigl[S_T\,1_{\{S_T>K\}}\bigr] - K\,P(S_T>K).\]The second term is the Gaussian tail:
\[P(S_T>K) \;=\; P(Y>\ln K) \;=\; \Phi\Bigl(\frac{-\ln K+m}{s}\Bigr).\]The first term is a partial expectation: the contribution of the upper tail, not divided by the tail probability. The $x$ in the integrand cancels the $1/x$ in the lognormal density:
\[\mathbb{E}\bigl[S_T\,1_{\{S_T>K\}}\bigr] \;=\; \int_{\ln K}^{\infty}\frac{e^{y}}{s\sqrt{2\pi}}\exp\Bigl(-\frac12\Bigl(\frac{y-m}{s}\Bigr)^2\Bigr)\,dy.\]The exponent is $y-(y-m)^2/(2s^2)$. Expand and complete the square, the same move as $\mathbb{E}[e^{aZ}]$:
\begin{align} y - \frac{(y-m)^2}{2s^2} &= \frac{2s^2 y - (y^2-2my+m^2)}{2s^2} = \frac{-y^2 + 2(m+s^2)y - m^2}{2s^2}. \end{align}
The identity $y^2-2(m+s^2)y=\bigl(y-(m+s^2)\bigr)^2-(m+s^2)^2$ turns the numerator into $-\bigl(y-(m+s^2)\bigr)^2+2ms^2+s^4$. Divide by $2s^2$:
\[y - \frac{(y-m)^2}{2s^2} \;=\; -\frac{\bigl(y-(m+s^2)\bigr)^2}{2s^2} + m + \frac{s^2}{2}.\]The constant $m+s^2/2$ comes out. What remains is a normal density with mean $m+s^2$ and variance $s^2$, truncated at $\ln K$:
\[\mathbb{E}\bigl[S_T\,1_{\{S_T>K\}}\bigr] \;=\; e^{m+s^2/2}\,\Phi\Bigl(\frac{-\ln K+m+s^2}{s}\Bigr). \tag{14}\]The cutoff turned the full MGF factor into that factor times a $\Phi$. The mean-shift $m\mapsto m+s^2$ is the gap between the two $\Phi$ arguments. Combining,
\[\mathbb{E}[(S_T-K)^+] \;=\; e^{m+s^2/2}\,\Phi(d_{+}) - K\,\Phi(d_{-}), \tag{15}\] \[d_{+} \;=\; \frac{-\ln K+m+s^2}{s}, \qquad d_{-} \;=\; \frac{-\ln K+m}{s}.\]If the premium were the discounted expected payoff under this law, it would be $e^{-r\tau}$ times $(15)$. That is the shape of Black–Scholes: two $\Phi$’s, a share piece and a cash piece.
What we do not yet have is $(m,s)$, and we do not yet know that the physical pair $(m,s)$ is the one to use. Stage 5 produces $(m,s)$ from the SDE. Stage 6 replaces the physical drift in $m$ by $r$. Until then, this is a calculus problem with two free parameters.
What each assumption is doing
The two-$\Phi$ shape is not a law of nature. It is a receipt for a short list of hypotheses. Perturb one and the formula either morphs (same skeleton, different inputs or an extra factor) or breaks (the completing-the-square step no longer lands on $\Phi$). That is the power the assumptions grant: they are what make a European call a pair of normal cdfs instead of a numerical integral, a PDE, or a tree.
$Y=\ln S_T$ is Gaussian. Completing the square turned $e^{y}$ times a normal density into another normal density. That is a property of $\exp(-\tfrac12 z^2)$, not of densities in general. If $\ln S_T$ is Student-$t$, the exponent is $\log(1+y^2/\nu)$ and there is no shift that produces another $t$ of the same family times a constant; you integrate numerically. If $S_T$ is a mixture of lognormals — stochastic volatility: $\sigma$ itself random, so $s$ is random and you mix over $s$ — then
\[\mathbb{E}[(S_T-K)^+] \;=\; \mathbb{E}\bigl[e^{m+s^2/2}\Phi(d_{+}(s)) - K\Phi(d_{-}(s))\bigr],\]an average of Black–Scholes prices, not a single pair of $\Phi$’s. Heston lives here. If you add jumps, $Y$ is Gaussian plus a Poisson number of extra Gaussians: Merton’s jump-diffusion is a sum of $\Phi$-pairs, one per jump-count. The skeleton morphs; the one-line formula $(15)$ breaks.
A single pair $(m,s)$, not a family indexed by strike or path. If volatility is a deterministic function of time, $s^2=\int_0^{\tau}\sigma(t)^2\,dt$ is still one number, and $(15)$ survives with that $s$. If $\sigma=\sigma(S,t)$ (local vol), $S_T$ is typically not lognormal, and there is no two-$\Phi$ of this shape — Dupire will still quote every strike in implied $\sigma(K)$, but that is the formula used backwards as a dictionary, not forwards as a model. If you let $s=s(K)$ depend on the strike you are pricing, you have already left the model: one lognormal cannot fit two smiles at once.
The payoff is $(S_T-K)^+$, a function of the terminal price only. The integral is over the law of $S_T$. It does not see the path. An American put can be exercised at any time, so the value depends on the whole path of opportunities; there is a free boundary, and no closed $\Phi$. A barrier option knocks out if $S$ touches a level before $T$; you need the joint law of $(S_T,\min S_t)$ or $(\,S_T,\max S_t)$. An Asian option pays on the average of $S$, which is not lognormal even when $S_T$ is. Cash-or-nothing — pay $1$ if $S_T>K$ — is not a break: it is the second term of the split, $e^{-r\tau}\Phi(d_{-})$. Asset-or-nothing is the first term. The call is those two claims glued together. Change the glue, and you are still in the family. Change the information the payoff sees, and you are not.
The strike $K$ is a known constant. It is the cutoff $\ln K$ in the integral. If the strike is itself random — average-strike Asian, or a quanto with a foreign asset in the strike — the cutoff is no longer a number, and $(14)$ does not apply. If you pay $(S_T-K)^+$ in a different currency, you have a second lognormal and a covariance; the formula morphs (still $\Phi$’s, extra $e^{q\tau}$ and a modified $s$).
Discounting is $e^{-r\tau}$ with $r$ deterministic. A constant $r$ factors out of the expectation. If $r_t$ is random and correlated with $S$, you must compute $\mathbb{E}\bigl[e^{-\int r}(S_T-K)^+\bigr]$; the discount no longer comes out, and you need a two-factor model (or a bond as numeraire — stage 7). If $r$ is deterministic but time-dependent, $e^{-r\tau}$ becomes $e^{-\int r}$, and $(15)$ survives with that factor. Deterministic $r$ is what lets a number sit in front of the two $\Phi$’s.
The law of $S_T$ is the law you take the expectation under. If you feed the physical $(m,s)$ — the one with $\mu$ in it — into $(15)$ and discount, you get a number. It is not the no-arbitrage price. The two-$\Phi$ shape is intact; the input $m$ is wrong. Stage 6 is the statement that the pricing law uses $r$ in place of $\mu$. Perturbing this assumption does not break the calculus. It prices a different lottery.
$S_T>0$ and the Jacobian $1/x$. That is the multiplicative hypothesis of stage 3. If you go back to an additive Gaussian, $S_T=S+\sigma\sqrt{\tau}\,Z$ (Bachelier), the integral is a $\Phi$ of $(S-K)/(\sigma\sqrt{\tau})$ with no logarithms, and prices can be negative. The formula modulates into a different closed form, used for rates after 2008 when yields could go through zero. The log in $d_{\pm}$ is not decoration. It is the Jacobian of stage 3, still visible in the answer.
No dividend (or a continuous yield that can be absorbed into $m$). If the stock pays a continuous yield $q$, the forward is $S e^{(r-q)\tau}$ instead of $S e^{r\tau}$, and $(15)$ morphs by $m\leftarrow m-q\tau$ and an extra $e^{-q\tau}$ on the share piece. The skeleton lives. A discrete cash dividend of size $D$ just before $T$ makes $S_T=S^_T-D$ with $S^$ lognormal; $S_T$ itself is not, and you integrate a shifted lognormal — doable, but not $(15)$ as written.
| Assumption | Perturb | Two \(\Phi\)'s? |
|---|---|---|
| \(\ln S_T\) Gaussian | Student-\(t\); mixture (Heston); jumps (Merton) | breaks; average of \(\Phi\)'s; sum of \(\Phi\)'s |
| one \((m,s)\) | \(\sigma(t)\) deterministic; \(\sigma(S,t)\); smile \(s(K)\) | survives as \(s^2=\int\sigma^2\); breaks; quoting machine |
| payoff \((S_T-K)^+\) | American; barrier; Asian; cash-or-nothing | breaks; breaks; breaks; is the second \(\Phi\) |
| fixed strike \(K\) | random strike; quanto | breaks; morphs (extra cov) |
| \(e^{-r\tau}\), \(r\) deterministic | \(r(t)\) deterministic; random \(r_t\) | survives; breaks (two-factor) |
| this law is the pricing law | physical \(\mu\) instead of \(r\) | shape lives, number is wrong |
| multiplicative, \(S_T>0\) | additive Gaussian (Bachelier) | different \(\Phi\), no \(\ln\) |
| no cash dividend | yield \(q\); discrete \(D\) | morphs (\(e^{-q\tau}\)); shifted integral |
The assumptions are doing a lot of work. They are also why a rain check on a stock has a two-line formula and a rain check on an average, or on a stock that can jump, does not. Stages 5–6 will choose $(m,s)$ inside this skeleton. They will not replace the skeleton. If you wanted a different skeleton, you would have had to perturb the list above.
5. A detour to Japan
The chain rule you already know is first-order Taylor. If $x$ moves by $dx$, then $f$ moves by $f’(x)\,dx$, and the next term $\tfrac12 f’‘(x)\,(dx)^2$ is discarded because it vanishes faster than $dx$. For a path with a tangent that discard is legal.
A Wiener path has no tangent. Each increment satisfies $(dW)^2=dt$, the same size as the clock, so the second-order term survives. In 1942 Kiyosi Itô put it back. The rest of this stage is that leftover, by hand, on $W^2$. Stage 6 spends it on $\ln S$: the extra $-\tfrac12\sigma^2\,dt$ in the log-drift is the $e^{s^2/2}$ of stage 3, booked in a different ledger.
Quadratic variation, by hand
Chop a year into four steps. Each step is $\pm\sqrt{1/4}=\pm 1/2$. Four heads ends at $+2$. Four tails ends at $-2$. Mixed paths end at $0$. The ending points disagree. The sum of the squared steps does not:
\[\bigl(\tfrac12\bigr)^2+\bigl(\tfrac12\bigr)^2+\bigl(\tfrac12\bigr)^2+\bigl(\tfrac12\bigr)^2 \;=\; 1\]on every path.
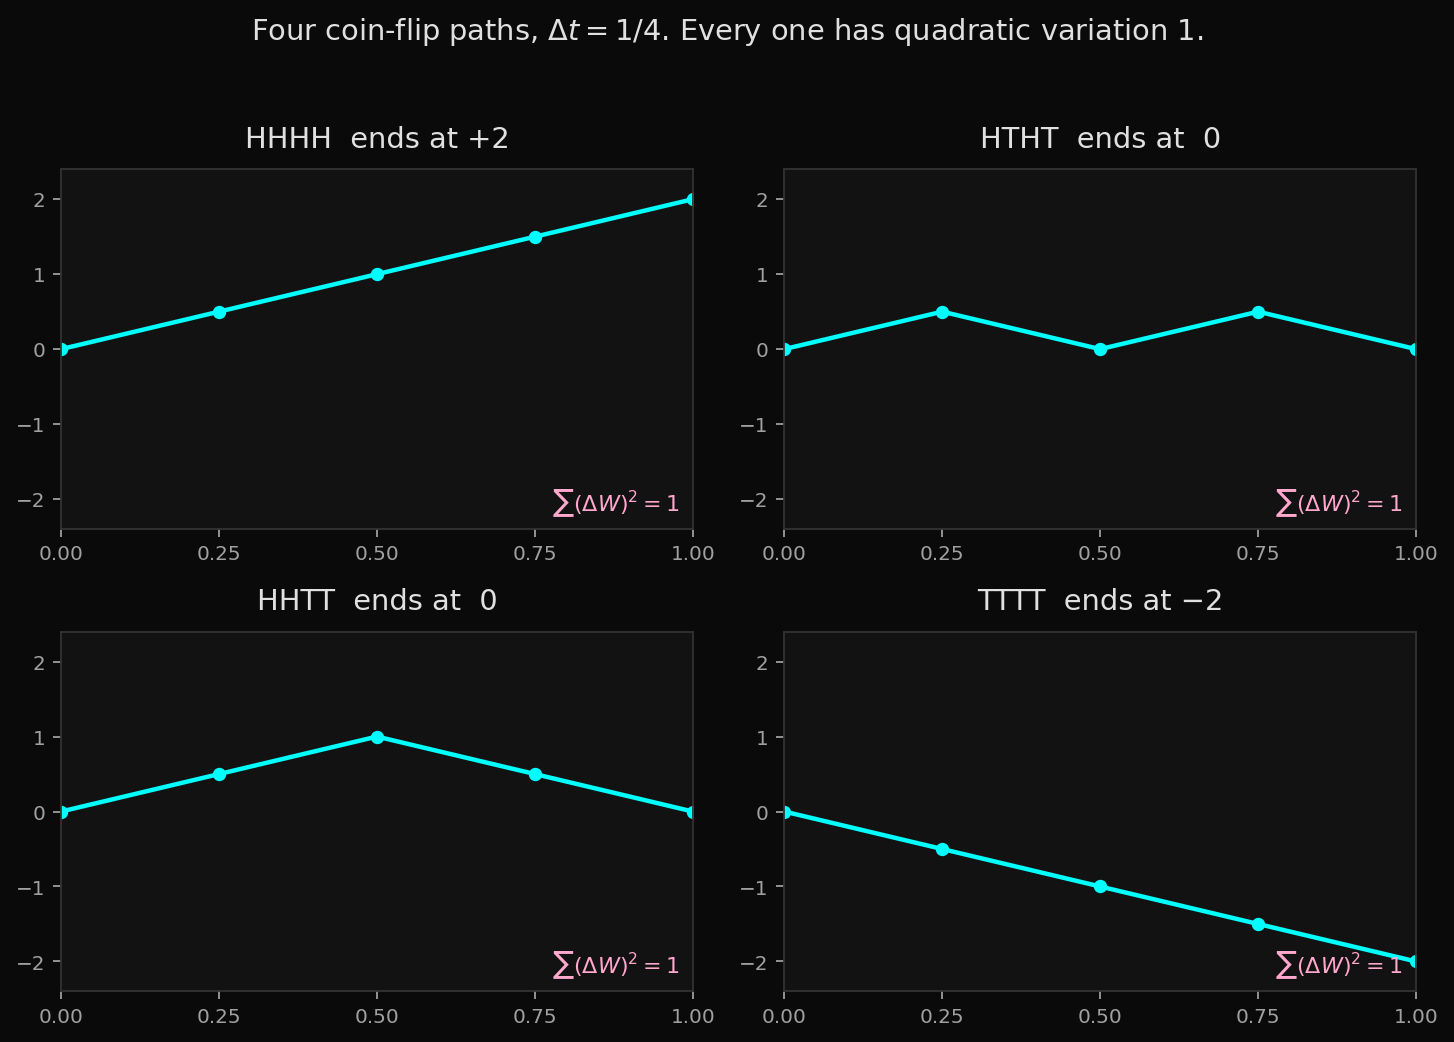
In the limit this is a theorem. Chop $[0,t]$ into $n$ steps $\Delta t=t/n$. Each increment satisfies $\mathbb{E}[(\Delta W_i)^2]=\Delta t$ and, because $\Delta W_i\sim\mathcal{N}(0,\Delta t)$, $\mathrm{Var}((\Delta W_i)^2)=2(\Delta t)^2$. The sum of squares has mean $t$ and variance $2t^2/n\to 0$. Convergence in $L^2$ to the constant $t$: $(dW_t)^2=dt$. Keep them.
The paths have, with probability $1$, no tangent line anywhere. You cannot write $dW_t/dt$. You can only write $dW_t$.
Itô on $W^2$
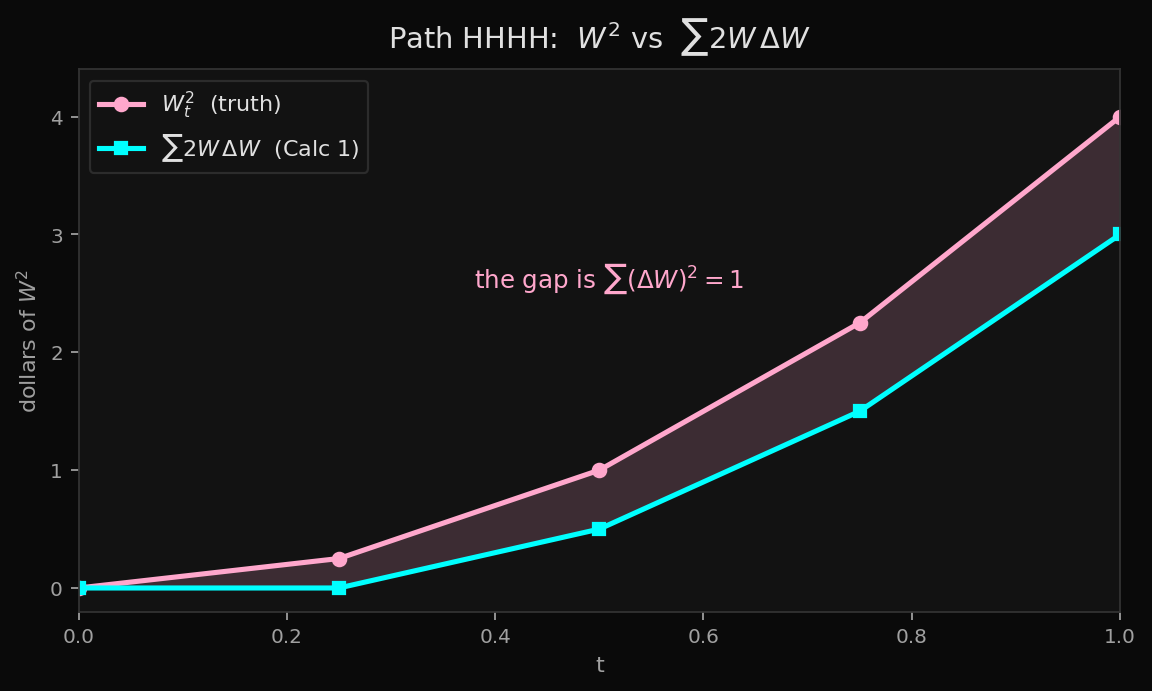
The chain rule on $f(x)=x^2$ says $\Delta f=2x\,\Delta x$. Taylor keeps the next term $(\Delta x)^2$. Calculus 1 throws that second term away. On the four-step path of four heads, $W=0,0.5,1,1.5,2$, so $W^2$ ends at $4$. The chain-rule running sum $\sum 2W\,\Delta W$ is
\[2\cdot 0\cdot\tfrac12 + 2\cdot\tfrac12\cdot\tfrac12 + 2\cdot 1\cdot\tfrac12 + 2\cdot\tfrac32\cdot\tfrac12 \;=\; 3.\]The leftover $\sum(\Delta W)^2=1$ makes up the difference: $3+1=4$.
Itô’s lemma is Taylor in two variables, with the multiplication table substituted in. Let $X$ satisfy $dX=a\,dt+b\,dW$, and let $f(t,x)$ be $C^{1,2}$. The second-order expansion is
\[\Delta f \;=\; f_t\,\Delta t + f_x\,\Delta x + \tfrac12 f_{xx}(\Delta x)^2 + f_{tx}\,\Delta t\,\Delta x + \tfrac12 f_{tt}(\Delta t)^2 + o(\Delta t).\]Feed in $\Delta x=a\,\Delta t+b\,\Delta W$. The table kills $(\Delta t)^2$ and $\Delta t\,\Delta W$, and sends $(\Delta x)^2\to b^2\Delta t$. What remains is
\[df(t,X_t) \;=\; \Bigl(f_t + a f_x + \tfrac12 b^2 f_{xx}\Bigr)dt + b f_x\,dW_t. \tag{3}\]The first two terms in the $dt$ coefficient are that same chain rule. The third is the leftover we just computed on $W^2$. For $f(x)=x^2$ and $X=W$ ($a=0$, $b=1$, $f_{xx}=2$), the correction is $dt$, and $d(W^2)=2W\,dW+dt$. Integrate: $W_t^2=2\int W\,dW+t$. At $t=1$ the extra $+1$ is the gap in the figure.
Stage 6 applies the same lemma to $\ln S$.
6. Derive from stochastic calculus
Four jobs: solve the SDE, see why $\mu$ is not in the price, plug into stage 4, and match the PDE.
Itô on $\ln S$
Apply $(3)$ to $f(s)=\ln s$ and to the stock $(2)$. Then $f_s=1/s$, $f_{ss}=-1/s^2$, and the leftover is $-\tfrac12\sigma^2\,dt$:
\begin{align}
d\ln S_t
&= \frac{1}{S_t}\,dS_t + \tfrac12\Bigl(-\frac{1}{S_t^2}\Bigr)(\sigma S_t\,dW_t)^2
&= \mu\,dt + \sigma\,dW_t - \tfrac12\sigma^2\,dt
&= \bigl(\mu - \tfrac12\sigma^2\bigr)dt + \sigma\,dW_t.
\end{align}
Integrate from $t$ to $T$. Write $\tau=T-t$, and $W_T-W_t\stackrel{d}{=}\sqrt{\tau}\,Z$ with $Z\sim\mathcal{N}(0,1)$:
\[S_T \;=\; S_t\exp\Bigl(\bigl(\mu-\tfrac12\sigma^2\bigr)\tau + \sigma\sqrt{\tau}\,Z\Bigr). \tag{4}\]This is the lognormal of stage 3, with
\[m \;=\; \ln S_t + \bigl(\mu-\tfrac12\sigma^2\bigr)\tau, \qquad s^2 \;=\; \sigma^2\tau.\]The $\tfrac12\sigma^2$ that left the log-drift is the $e^{s^2/2}$ from the MGF. It returns in the mean of the stock: $\mathbb{E}[S_T\mid S_t]=S_t e^{\mu\tau}$. Nothing is lost. It is booked in a different ledger.
Assumptions, said once. The stock follows $(2)$ with $\mu,\sigma$ constant (one Brownian motion; no jumps). The rate $r$ is a known constant; you may borrow or lend any amount at $r$. No dividends. No arbitrage, continuous trading, a complete market: every payoff can be manufactured from the stock and the money-market account, because there is one source of noise and two traded assets. Fractional holdings and short sales are allowed; there are no transaction costs.
Why not $\mu$: a two-leaf tree
The physical pair $(m,s)$ is not the one that prices the call. A cartoon is enough.
A stock trades at $100$. In one year it is either $200$ or $50$. No interest. A call struck at $100$ pays $100$ or $0$.
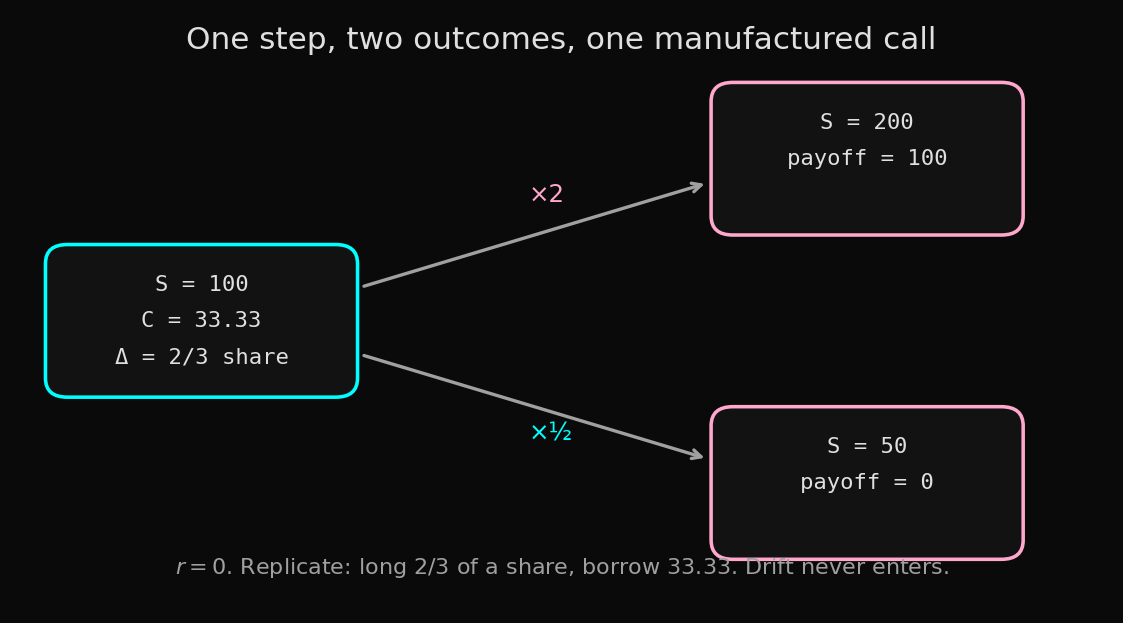
Hold $\Delta$ shares and $B$ dollars in cash (negative $B$ means you borrowed). Match the call on both leaves:
\[200\Delta + B \;=\; 100, \qquad 50\Delta + B \;=\; 0.\]Subtract: $\Delta=2/3$, then $B=-33.33$. Today the portfolio costs $\tfrac23\cdot 100-33.33=33.33$. If the call sold for anything else, you would buy the cheap side and sell the dear side:
| Quote | Today's cash | At expiry |
|---|---|---|
| \(40\) (dear) | sell call, buy portfolio: \(+6.67\) | portfolio covers the call; keep \(6.67\) |
| \(33.33\) | nothing to do | nothing to do |
| \(20\) (cheap) | buy call, sell portfolio: \(+13.33\) | call covers the portfolio; keep \(13.33\) |
A free lunch if the quote is not $33.33$. The physical probability that the stock doubles never entered. Two linear equations.
The unique probability $p^$ that makes the stock a fair game is $p^=(1-1/2)/(2-1/2)=1/3$, and $C=p^\cdot 100=33.33$ again. With interest, a dollar grows by a factor $R$ over the step, $p^=(R-d)/(u-d)$, and the call is the discounted fair-game expectation. That $p^*$ is not the real-world chance of the up-move. It is the probability that makes the stock a martingale, in the sense of stage 2.
A tree calibrated to $r=5\%$, $\sigma=20\%$, one year, $S=K=100$, with Cox–Ross–Rubinstein $u=e^{\sigma\sqrt{\Delta t}}$, $d=1/u$, walks from $12.16$ ($n=1$) to $10.45$ ($n\to\infty$):
| \(n\) | 1 | 2 | 4 | 8 | 16 | 32 | 64 | 128 | \(\infty\) |
|---|---|---|---|---|---|---|---|---|---|
| call | 12.16 | 9.54 | 9.97 | 10.21 | 10.33 | 10.39 | 10.42 | 10.43 | 10.45 |
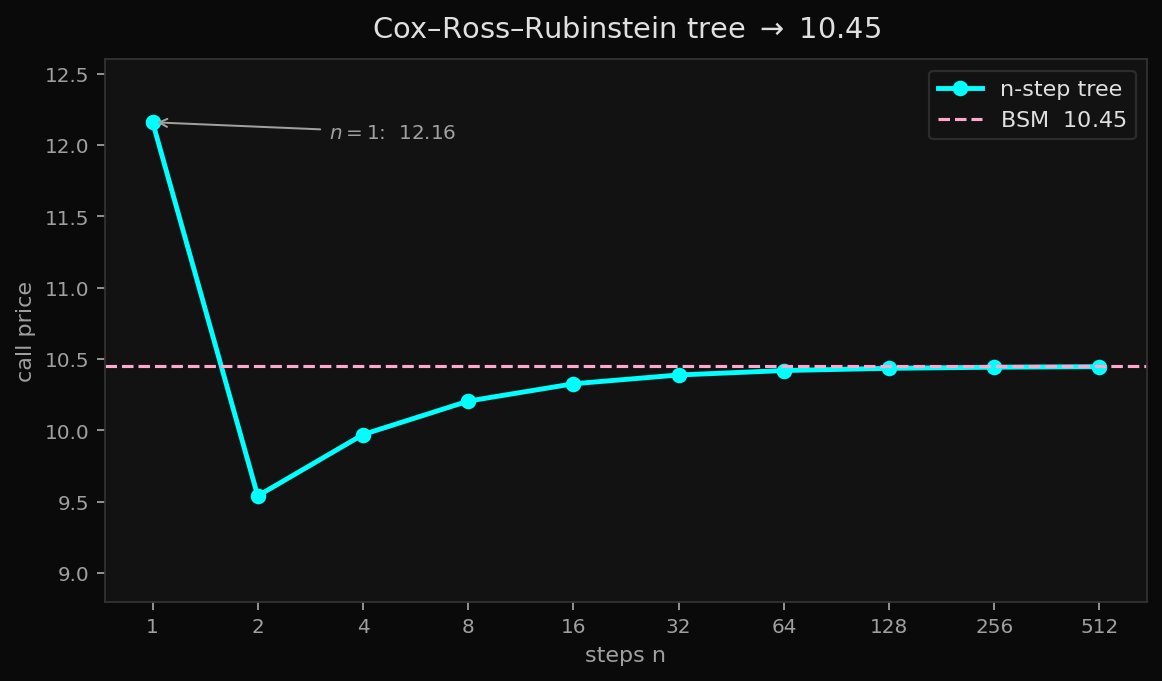
The $n=2$ dip is a coarse histogram of a bell curve. From $n=4$ the walk is toward $10.45$. That is the number. The closed form is stage 4, with the fair-game $(m,s)$.
Girsanov, from two Gaussians
On the tree, the likelihood ratio on one step is $p^/p$ on up and $(1-p^)/(1-p)$ on down. Then $\mathbb{E}^[X]=\mathbb{E}[X\,\xi]$. Over $n$ steps, $\xi$ is the product of those ratios. That product *is Girsanov, before the limit.
One Gaussian. Under $\mathbb{P}$, $W_t\sim\mathcal{N}(0,t)$. We want $\mathbb{Q}$ under which $W_t\sim\mathcal{N}(-\theta t,\,t)$, so that $W_t+\theta t$ is standard Wiener. The density ratio is
\[\xi_t \;=\; \exp\bigl(-\theta W_t - \tfrac12\theta^2 t\bigr).\]For any test function, $\mathbb{E}^{\mathbb{Q}}[f(W_t)]=\mathbb{E}^{\mathbb{P}}[f(W_t)\,\xi_t]$. Independent increments multiply the same ratio across steps. That is Girsanov’s theorem, from the Gaussian pdf.
Which $\theta$. Rewrite $(2)$ as
\[dS \;=\; r S\,dt + \sigma S\Bigl(dW + \frac{\mu-r}{\sigma}\,dt\Bigr).\]The process in parentheses is Wiener plus a constant drift $\theta=(\mu-r)/\sigma$, the market price of risk. Girsanov with that $\theta$ makes $W^{\mathbb{Q}}_t=W_t+\theta t$ a Wiener process under $\mathbb{Q}$, and
\[dS_t \;=\; r S_t\,dt + \sigma S_t\,dW_t^{\mathbb{Q}}. \tag{5}\]Under $\mathbb{Q}$, $(4)$ holds with $\mu$ replaced by $r$:
\[S_T \;=\; S_t\exp\Bigl(\bigl(r-\tfrac12\sigma^2\bigr)\tau + \sigma\sqrt{\tau}\,Z\Bigr), \qquad Z\sim\mathcal{N}(0,1)\text{ under }\mathbb{Q}. \tag{7}\]The discounted stock $S_t e^{-rt}$ is a martingale under $\mathbb{Q}$. The call is the discounted fair-game expectation:
\[C \;=\; e^{-r\tau}\,\mathbb{E}^{\mathbb{Q}}\bigl[(S_T-K)^+\bigr]. \tag{6}\]Two traders who disagree about $\mu$ still agree on $C$ if they agree on $\sigma$. $\Delta=2/3$ did not ask who thought the stock would double.
Plug in
Under $\mathbb{Q}$,
\[m \;=\; \ln S_t + \bigl(r-\tfrac12\sigma^2\bigr)\tau, \qquad s \;=\; \sigma\sqrt{\tau}.\]Feed into $(15)$. Then $e^{m+s^2/2}=S_t e^{r\tau}$, so the discounted share-piece is $S_t\Phi(d_1)$ and the discounted cash-piece is $K e^{-r\tau}\Phi(d_2)$, with
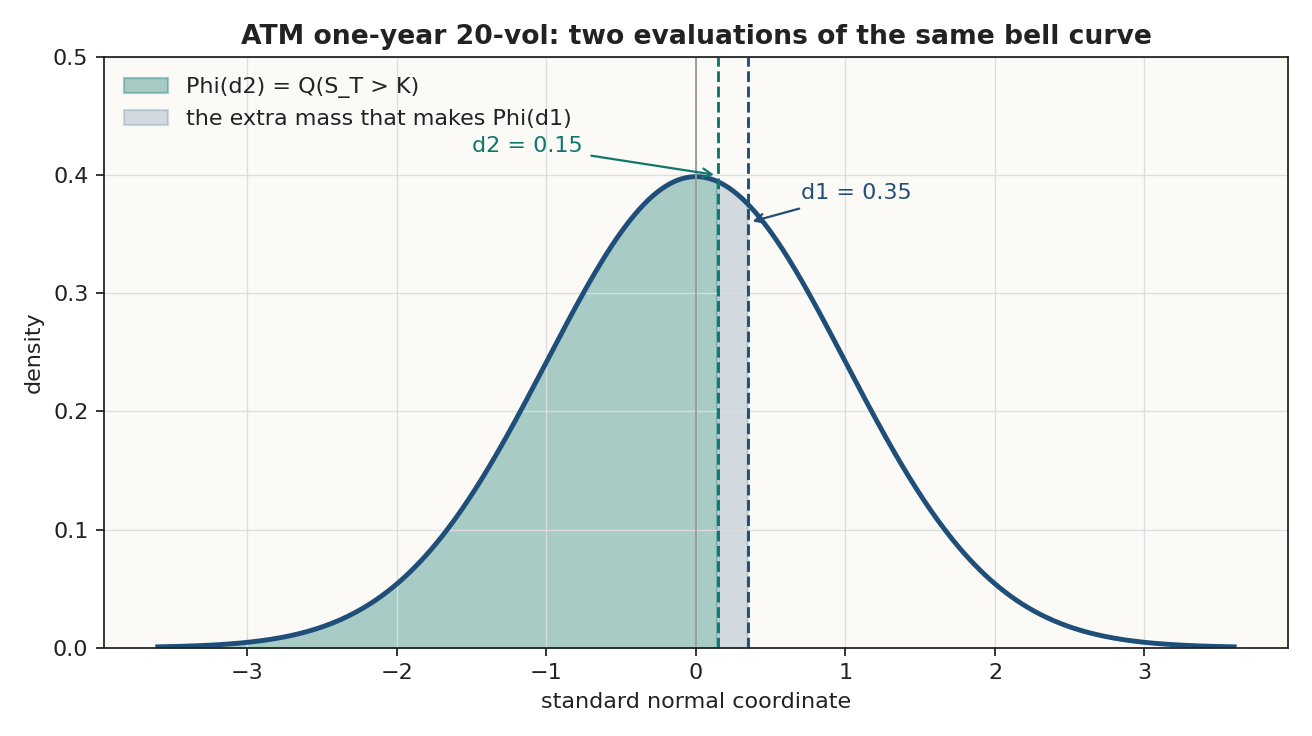
\[C \;=\; S_t\,\Phi(d_1) - K e^{-r\tau}\,\Phi(d_2), \tag{1}\] \[d_1 \;=\; \frac{\ln(S_t/K)+\bigl(r+\tfrac12\sigma^2\bigr)\tau}{\sigma\sqrt{\tau}}, \qquad d_2 \;=\; d_1 - \sigma\sqrt{\tau}.\]For the rain check: $S=K=100$, $\tau=1$, $r=0.05$, $\sigma=0.20$. Then $d_2=0.15$, $d_1=0.35$, $\Phi(0.15)\approx 0.560$, $\Phi(0.35)\approx 0.637$, and
\[C \;=\; 100\cdot 0.637 - 100\cdot e^{-0.05}\cdot 0.560 \;\approx\; 63.68-53.23 \;=\; 10.45.\]We guessed a working premium of $10$. The formula charges $10.45$. Close, for a rain check. $\Phi(d_1)\approx 0.637$ is the delta: you manufacture this call by holding about two-thirds of a share, the $\Delta=2/3$ of the tree, smeared across spots. $\Phi(d_2)\approx 0.560$ is the risk-neutral chance of exercise.
The same arithmetic in Python, standard library only:
from math import log, exp, sqrt, erf

def Phi(x):
    return 0.5 * (1 + erf(x / sqrt(2)))

S, K, r, sig, tau = 100, 100, 0.05, 0.20, 1.0
d1 = (log(S / K) + (r + 0.5 * sig**2) * tau) / (sig * sqrt(tau))
d2 = d1 - sig * sqrt(tau)
C = S * Phi(d1) - K * exp(-r * tau) * Phi(d2)
print(C)  # 10.450583572185565
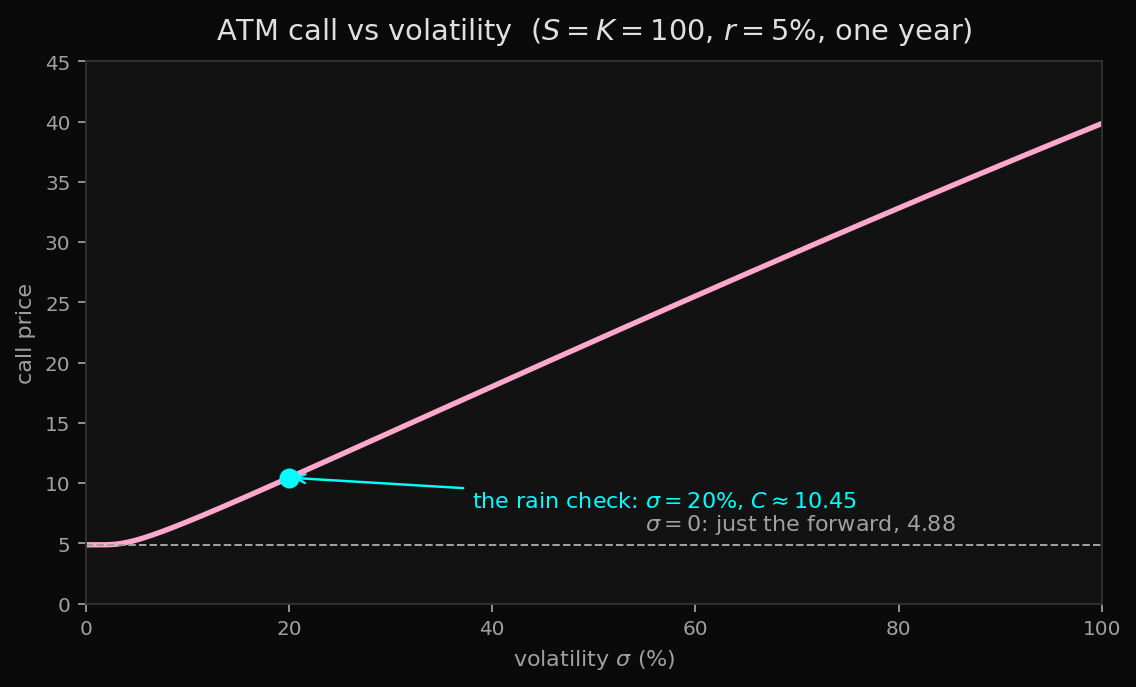
Volatility is the only input you cannot read off a newspaper.
| \(\sigma\) | call | what happened |
|---|---|---|
| \(0\) | \(4.88\) | no wander: just the forward \(S-Ke^{-r\tau}\) |
| \(10\%\) | \(6.80\) | |
| \(20\%\) | \(10.45\) | the rain check |
| \(40\%\) | \(18.02\) | |
| \(100\%\) | \(39.84\) | almost a coin-flip on the stock itself |
Put-call parity. A European call minus a European put, same strike and expiry, is a forward: you will buy the stock at $K$ at time $T$ whether $S_T$ is above or below. A forward on a non-dividend stock is worth $S_t-Ke^{-r\tau}$, so $C-P=S_t-Ke^{-r\tau}$ and
\[P \;=\; K e^{-r\tau}\,\Phi(-d_2) - S_t\,\Phi(-d_1).\]For the rain-check numbers, $P\approx 5.57$, and $C-P=4.88$, the $\sigma=0$ row.
The PDE, and the heat equation
Black and Scholes started from a portfolio $\Pi=-V+\Delta S$. Expand $dV$ with $(3)$, choose $\Delta=V_S$ so the $dW$ terms cancel (delta-hedging), and require the now-riskless $\Pi$ to earn $r$. The $dW$ cancellation eats $\mu$, just as $\Delta=2/3$ did. The Black–Scholes PDE is
\[V_t + rS V_S + \tfrac12\sigma^2 S^2 V_{SS} - rV \;=\; 0, \tag{17}\]with $V(S,T)=(S-K)^+$. For the rain-check numbers, $\Delta=V_S=\Phi(d_1)\approx 0.637$.
This is a linear parabolic PDE. You have seen one: the heat equation. Let $\tau=T-t$, $x=\ln(S/K)$, $V(S,t)=U(x,\tau)$. Then $V_t=-U_\tau$, $V_S=U_x/S$, and $S^2 V_{SS}=U_{xx}-U_x$. Substitute:
\[U_\tau \;=\; \tfrac12\sigma^2 U_{xx} + \bigl(r-\tfrac12\sigma^2\bigr)U_x - r U.\]Rescale $\tilde\tau=\sigma^2\tau/2$, set $k=2r/\sigma^2$, and kill lower-order terms with $U=e^{\alpha x+\beta\tilde\tau}W$, $\alpha=(1-k)/2$, $\beta=\alpha^2+(k-1)\alpha-k$. Then $W_{\tilde\tau}=W_{xx}$. (Rain-check numbers: $k=2.5$, $\alpha=-3/4$, $\beta=-49/16$.)
The heat kernel is $G(x,\tilde\tau)=(4\pi\tilde\tau)^{-1/2}\exp(-x^2/(4\tilde\tau))$, an expectation against $\mathcal{N}(0,2\tilde\tau)$. And $2\tilde\tau=\sigma^2\tau=\mathrm{Var}(\ln S_T)$ under $\mathbb{Q}$. The heat kernel is the lognormal. Feynman–Kac, here, is that kernel, run at variance $\sigma^2\tau$.
7. Change of numeraire
Stage 4 split the call into a share-or-nothing and a cash-or-nothing. Under $\mathbb{Q}$, the cash-or-nothing’s probability is $\Phi(d_2)$. The share-or-nothing’s $\Phi(d_1)$ is the same event, measured in a different unit of account.
A numeraire is the unit you quote prices in. Dollars: the money-market account $B_t=e^{rt}$. Shares: the stock $S_t$. For each choice there is a measure that makes every asset, divided by that numeraire, a martingale.
| Numeraire | Measure | Martingale | exercise probability | Role in (1) |
|---|---|---|---|---|
| bond \(B_t=e^{rt}\) | \(\mathbb{Q}\) | \(S_t/B_t\) | \(\Phi(d_2)\) | multiplies the cash \(Ke^{-r\tau}\) |
| stock \(S_t\) | \(\mathbb{Q}^{S}\) | \(B_t/S_t\) | \(\Phi(d_1)\) | multiplies the share \(S_t\) |
The density ratio that changes $\mathbb{Q}$ into $\mathbb{Q}^{S}$ is the terminal value of the new numeraire, rebased:
\[\frac{d\mathbb{Q}^{S}}{d\mathbb{Q}} \;=\; \frac{S_T}{S_t e^{r\tau}}.\]Under $\mathbb{Q}$, from $(7)$,
\[\frac{S_T}{S_t e^{r\tau}} \;=\; \exp\bigl(-\tfrac12\sigma^2\tau + \sigma\sqrt{\tau}\,Z\bigr).\]That is the Girsanov density $\xi=\exp(-\theta W-\tfrac12\theta^2 t)$ of stage 6, with $\theta=-\sigma$ and $W_{\tau}=\sqrt{\tau}\,Z$. The tilt adds $\sigma\sqrt{\tau}$ to $Z$. The event ${S_T>K}$ is ${Z>-d_2}$ under $\mathbb{Q}$; after the tilt it is ${Z+\sigma\sqrt{\tau}>-d_2}={Z>-d_1}$, so
\[\mathbb{Q}^{S}(S_T>K) \;=\; \Phi(d_1).\]The share-or-nothing is therefore $S_t\,\Phi(d_1)$: today’s share, times the exercise probability in share units. The cash-or-nothing is $Ke^{-r\tau}\,\Phi(d_2)$: discounted strike, times the exercise probability in dollar units. That is $(1)$, with both $\Phi$’s now ordinary probabilities, each belonging to the numeraire that multiplies it.
The same Itô computation on $f=1/S$ produces the SDE for the inverse stock, whose lognormal is the one $\mathbb{Q}^{S}$ sees. The density ratio above is enough: it is Girsanov with the opposite tilt.
Limitations
The theorem we proved is narrower than the word “option.” It prices a European call on a stock that pays no dividend, driven by one Wiener process with a constant $\sigma$, in a market where you can trade continuously at a known rate $r$. Change any of those and either the two-$\Phi$ skeleton morphs — same shape, different inputs — or it breaks.
Dividends
The rain-check stock paid nothing while you held it. Under the fair-game measure $\mathbb{Q}$, its drift had to be $r$: otherwise you could pocket the excess over the bond. If the stock instead pays a continuous yield $q$ — a cash stream $qS\,dt$ while you hold it — the capital-gain drift under $\mathbb{Q}$ must be $r-q$. Total return, gain plus yield, equals $r$. Any more is a free lunch.
The prepaid forward is then $S_t e^{-q\tau}$ instead of $S_t$. Stage 4’s two integrals still close. The share piece picks up $e^{-q\tau}$, and $r$ is replaced by $r-q$ inside $d_1$ and $d_2$:
\[C \;=\; S_t e^{-q\tau}\,\Phi(d_1) - K e^{-r\tau}\,\Phi(d_2).\]Give the rain-check stock a $2\%$ yield. Then $d_1=0.25$, $d_2=0.05$, and $C\approx 9.23$, cheaper than $10.45$: the stock itself now pays you, so the call is less of a reason to hold.
The same skeleton prices three cousins, once you name what $q$ is.
- A call on an index. The stocks in the basket pay dividends, so the index has a yield $q$.
- A call on a foreign currency (Garman–Kohlhagen). Holding euros earns the euro interest rate $r_f$; that rate is $q$.
- A call on a futures (Black 1976). You put up no cash to hold the futures, so you save the financing $r$. That saving is a yield $q=r$, and the formula collapses to $e^{-r\tau}\bigl[F\Phi(d_1)-K\Phi(d_2)\bigr]$.
A discrete cash dividend of size $D$ just before $T$ is a different animal: $S_T$ is then a lognormal minus $D$, which is not lognormal, and $(1)$ as written does not apply.
The smile
The model has one $\sigma$ for every strike. After the 1987 crash, out-of-the-money puts — insurance against a crash — started trading at prices no single $\sigma$ could fit. Low strikes implied a higher $\sigma$ than the rain check did.
Implied volatility is the dictionary that survived. Given a quoted price, it is the number $\sigma_{\mathrm{imp}}$ you feed into $(1)$ to recover that quote. Our formula at $20\%$ says $10.45$; if the market shows $12$, implied vol is some number above $20\%$. Plot $\sigma_{\mathrm{imp}}$ against strike and you get a U in FX (a smile) and a downward slope in equities (a smirk: crash insurance is dear). Traders still quote “vol $22$” rather than a dollar price, because that number compares across strikes and tenors. They are using $(1)$ backwards as a language. They do not believe $\ln S_T$ is Gaussian.
Jumps, wandering vol, early exercise
Three ways the one-Wiener story fails.
Wiener paths are continuous: they cannot gap overnight. A crash is a gap. Merton added Poisson jumps on top of the Wiener process. You cannot hedge a jump with $\Delta$ shares, so the market is no longer complete, and the price is a sum of $\Phi$-pairs, one per jump-count, not a single pair.
$\sigma$ need not be a constant. If $\sigma_t$ itself wanders (Heston), then $s$ is random and the call is an average of Black–Scholes prices, one per realised $s$. If instead $\sigma=\sigma(S,t)$ is fitted today so that every quoted strike is recovered (Dupire’s local vol), $S_T$ is typically not lognormal at all: the two-$\Phi$ formula is being used as a quoting machine, not as a model.
A European contract can be exercised only at $T$. An American put can be exercised at any time. If the stock is near zero, taking $K$ in cash now beats waiting. That is a free boundary; there is no two-$\Phi$ of this shape. The binomial tree of stage 6 is the honest computation: at each node, take the max of exercise and hold. (An American call on a non-dividend stock is never exercised early — the European formula still holds — because the stock pays you nothing for owning it now rather than later.)
What was proved
What has been proved is a theorem about a complete market driven by one Wiener process: the unique no-arbitrage price of $(S_T-K)^+$ is $(1)$. Using that theorem as a price, as a quoting convention, or as the first term of an approximation is a separate decision.
Seven stages: the contract; the noise, the fair game, and the stock; the lognormal; a calculus integral; Itô; the SDE plus Girsanov; a change of unit. The rain check is $10.45$.
Cheers.
References
- Fabrice Douglas Rouah, Four Derivations of the Black-Scholes Formula. Local copy. Wayback, 19 July 2024.
- F. Black and M. Scholes, The Pricing of Options and Corporate Liabilities, JPE 81 (1973).
- R. C. Merton, Theory of Rational Option Pricing, Bell Journal 4 (1973).
- J. C. Cox, S. A. Ross, and M. Rubinstein, Option Pricing: A Simplified Approach, J. Financial Economics 7 (1979). The $n$-step tree.
- K. Itô, On Stochastic Differential Equations, Mem. AMS (1951).
- J. Hull, Options, Futures, and Other Derivatives.
- S. Shreve, Stochastic Calculus for Finance II.
- E. Derman and M. B. Miller, The Volatility Smile.